Internal and external audits play an important role in maintaining financial accuracy, improving business operations, and supporting compliance for companies in the United Arab Emirates. A well-organized audit process helps business owners understand their financial position, identify weaknesses in internal controls, and maintain reliable accounting records.
Although both audits examine business activities, they serve different purposes. Internal audits services focus on evaluating risks, controls, and operational efficiency, while external audits provide an independent opinion on financial statements. The requirements applicable to a company depend on its legal structure, business activity, regulatory environment, and free zone or licensing authority.
Following a UAE Internal and External Audit Compliance Guide helps businesses organize their documents, prepare their accounting records, and address potential issues before an audit begins.
Table of Contents
1. Understanding Internal and External Audits
What Is an Internal Audit?
The UAE Internal and External Audit Compliance Guide explains how an internal audit independently reviews a company’s processes, financial controls, risk management, and operations. It helps identify weaknesses and improve business efficiency.
Internal auditors review purchasing, payroll, inventory, payments, accounting systems, and compliance processes to reduce errors and prevent fraud.
The scope and frequency of internal audits depend on business risks, governance, and applicable UAE regulatory requirements.
What Is an External Audit?
An external audit is an independent examination of a company’s financial statements by a qualified auditor. The UAE Internal and External Audit Compliance Guide helps businesses understand audit procedures and financial reporting requirements.
The process includes reviewing accounting records, verifying balances, checking documents, and assessing internal controls.
In the UAE, audited financial statements are required for taxable persons with revenue exceeding AED 50 million and qualifying free zone persons, subject to applicable legislation.
2. Important Distinctions Between Internal and External Audits
Internal and external audits complement each other, but their objectives are different.
| Comparison | Internal Audit | External Audit |
| Main purpose | Improve controls, processes, and risk management | Provide an independent opinion on financial statements |
| Primary users | Management, owners, and governance committees | Shareholders, regulators, lenders, and other stakeholders |
| Scope | Operations, controls, compliance, and risks | Financial statements and related audit evidence |
| Frequency | Based on the audit plan and business risks | Usually annual when required |
| Reporting | Findings and recommendations for management | Independent audit opinion and related reports |
| Independence | Must be appropriately positioned to work objectively | Must remain independent of the audit client |
Understanding these differences helps businesses prepare the right documents and assign responsibilities before the audit begins.
3. Internal and External Audit Checklist for UAE Businesses
The UAE Internal and External Audit Compliance Guide provides a structured checklist to help finance teams identify missing records, reconcile balances, and prepare supporting documents for auditors. Adapt the checklist to your company’s industry and regulatory requirements.
A. Financial Records Checklist
- Create the profit and loss statement and balance sheet.
- Update the general ledger and subsidiary ledgers.
- Prepare the balance sheet and profit and loss statement.
- Reconcile bank accounts and investigate outstanding items.
- Review accounts receivable and accounts payable balances.
- Verify revenue, expenses, and supporting invoices.
- Update the fixed asset register and depreciation calculations.
- Reconcile inventory records with physical stock counts.
- Review loans, liabilities, provisions, and accrued expenses.
- Confirm that significant transactions have supporting documentation.
Maintaining accurate records makes the audit process more efficient and helps auditors trace transactions to their original evidence.
B. Corporate and Legal Documents Checklist
- Keep the trade license and incorporation documents available.
- Maintain current ownership and shareholder information.
- Organize board resolutions and meeting minutes where applicable.
- Maintain relevant bank facility and loan agreements.
- Review major customer and supplier contracts.
- Keep records of significant business transactions.
- Check the audit appointment and engagement documentation.
- Confirm any reporting requirements imposed by the relevant free zone or regulator.
Companies should also ensure that their accounting records are consistent with their legal documents and reported business activities.
C. UAE Tax Compliance Checklist
- Reconcile VAT returns with accounting records.
- Examine credit notes, tax bills, and supporting documentation.
- Check corporate tax registration and filing records where applicable.
- Reconcile accounting profit with taxable income calculations.
- Retain documents supporting deductible expenses and tax adjustments.
- Review related-party transactions where relevant.
- Confirm that tax returns and payments have been completed within applicable deadlines.
- Maintain records supporting any applicable tax relief or exemption.
The Federal Tax Authority emphasizes that businesses subject to corporate tax must retain records supporting their tax returns and other required submissions. These may include transaction records, asset details, liabilities, and ownership information.
4. Internal Audit Procedures for UAE Businesses
An effective internal audit follows a planned process rather than relying on occasional document reviews.
- Step 1: Identify Business Risks: Begin by identifying areas where financial losses, errors, fraud, or compliance issues could occur. Common examples include unauthorized payments, inaccurate inventory records, weak credit controls, and incomplete financial reporting.
- Step 2: Develop an Audit Plan: Set clear objectives, define the scope, assign responsibilities, and establish a suitable timetable. High-risk business activities may require more frequent or detailed reviews.
- Step 3: Review Internal Controls: Examine how transactions are authorized, recorded, approved, and monitored. Check whether appropriate segregation of duties exists, especially for payments, payroll, purchasing, and financial reporting.
- Step 4: Test Transactions and Records: Select relevant transactions and compare them with invoices, contracts, approvals, bank statements, and accounting entries. Investigate unusual transactions, missing documents, and unexplained differences.
- Step 5: Document Findings: Record the issue, supporting evidence, potential impact, and recommended corrective action. Findings should be clear enough for management to understand and address.
- Step 6: Follow Up on Corrective Actions: Assign responsibility and target dates for resolving identified issues. Review progress to confirm that agreed improvements have been implemented effectively.
5. External Audit Procedures for UAE Companies
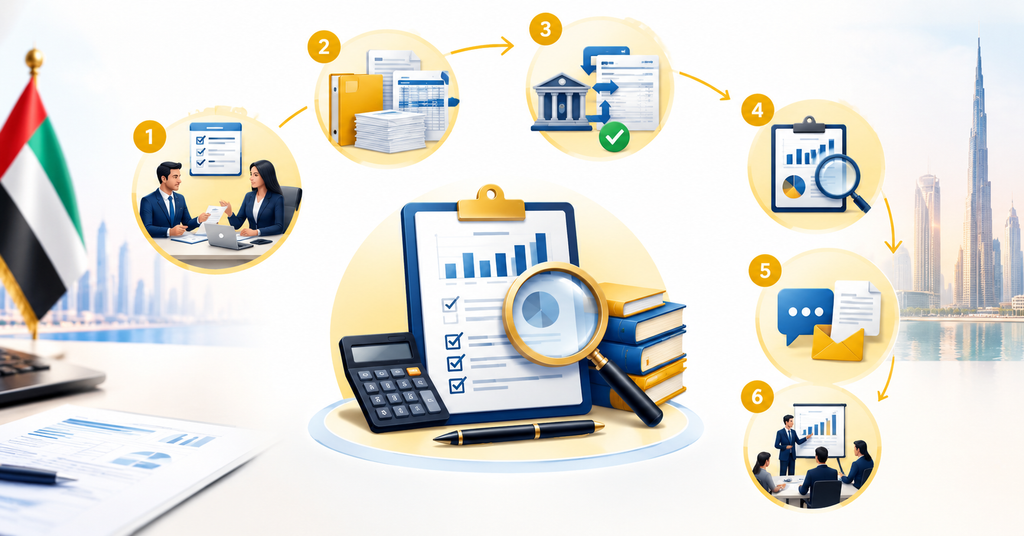
External audit procedures under the UAE Internal and External Audit Compliance Guide are designed to obtain sufficient appropriate evidence to support the auditor’s opinion on the financial statements.
- Step 1: Confirm the Audit Scope: Agree on the reporting period, financial reporting framework, audit responsibilities, and expected deliverables with the appointed auditor.
- Step 2: Submit Financial Records: Provide the trial balance, general ledger, financial statements, bank reconciliations, invoices, contracts, asset schedules, and other requested documents.
- Step 3: Reconcile Account Balances: Investigate differences between accounting records and third-party statements, including bank confirmations, customer balances, and supplier statements.
- Step 4: Verify Material Transactions: The auditor may test revenue, expenses, assets, liabilities, and significant estimates based on assessed risks and materiality.
- Step 5: Address Audit Queries: Respond promptly to questions and provide supporting evidence. Correct identified errors where appropriate.
- Step 6: Review the Audit Outcome: Discuss adjustments, findings, and control weaknesses with the auditor. Management remains responsible for the financial statements, while the external auditor provides an independent audit opinion.
6. Common Audit Preparation Mistakes to Avoid
UAE businesses can improve audit readiness by following the UAE Internal and External Audit Compliance Guide and avoiding these common problems:
Overlooking applicable requirements: Businesses should check relevant corporate, tax, regulatory, and free zone rules. Preparing records throughout the year is generally more effective than attempting to organize everything immediately before the audit.
Incomplete documentation: Missing invoices, contracts, approvals, or reconciliations can delay audits.
Unreconciled accounts: Differences between bank statements and accounting records should be resolved before the audit.
Incorrect expense classification: Personal, capital, and operating expenses must be recorded correctly.
Weak internal controls: Unclear approval processes can increase errors and unauthorized transactions.
Late preparation: Delaying reconciliations and schedules can create pressure on finance teams.
Unresolved audit findings: Repeated issues may indicate ineffective corrective actions.
7. Best Practices for Maintaining Audit Readiness
Businesses can strengthen their audit preparation by maintaining consistent accounting procedures and reviewing records regularly as part of the UAE Internal and External Audit Compliance Guide.
First, establish a monthly closing process that includes bank reconciliation, ledger review, and verification of outstanding balances. Second, use accounting software with proper access controls and an audit trail. Third, assign responsibility for maintaining financial schedules and supporting documents.
Management should review internal audit findings, monitor compliance deadlines, and retain records as required by applicable laws. Organising digital documents by financial year and transaction type makes information easier to retrieve.
The UAE Internal and External Audit Compliance Guide should be reviewed annually and updated whenever the business expands, changes its legal structure, enters a new market, or faces additional regulatory requirements.
Conclusion
A well-planned audit process helps UAE businesses maintain reliable financial records, improve internal controls, manage risks, and meet reporting requirements. By following the UAE Internal and External Audit Compliance Guide, companies can organise documents, identify discrepancies early, and prepare for audits more effectively.
Singiri & Co – Accounting & Bookkeeping LLC can assist businesses in Dubai and across the UAE with accounting records, financial statement preparation, internal controls, and audit readiness to help them meet their audit requirements.
FAQS
1. What is the difference between internal and external audits in the UAE?
Internal audits review business processes and risks, while external audits independently examine financial statements.
2. Which documents are required for a UAE company audit?
Common documents include financial statements, bank statements, invoices, ledgers, contracts, and tax records.
3. Are all UAE companies required to undergo an external audit?
Not all companies. Requirements depend on applicable laws, free zone rules, licence conditions, and other regulations.
4. How often should a business conduct an internal audit?
The frequency depends on business size, risk levels, operations, and regulatory requirements.
5. How can a UAE business prepare for an external audit?
Finalise accounts, reconcile balances, organise supporting documents, and update tax, asset, and inventory records.
6. Why is audit readiness important for UAE businesses?
Audit readiness improves financial accuracy, supports compliance, identifies errors early, and reduces audit delays.